On this page
Tax season is much easier when you start early and know exactly what to gather. Whether you file a simple personal return or own a business, rental property or investments, this guide walks through the documents to collect, the mistakes we see most often and how to make the whole process smooth from January to April.
The documents most people need
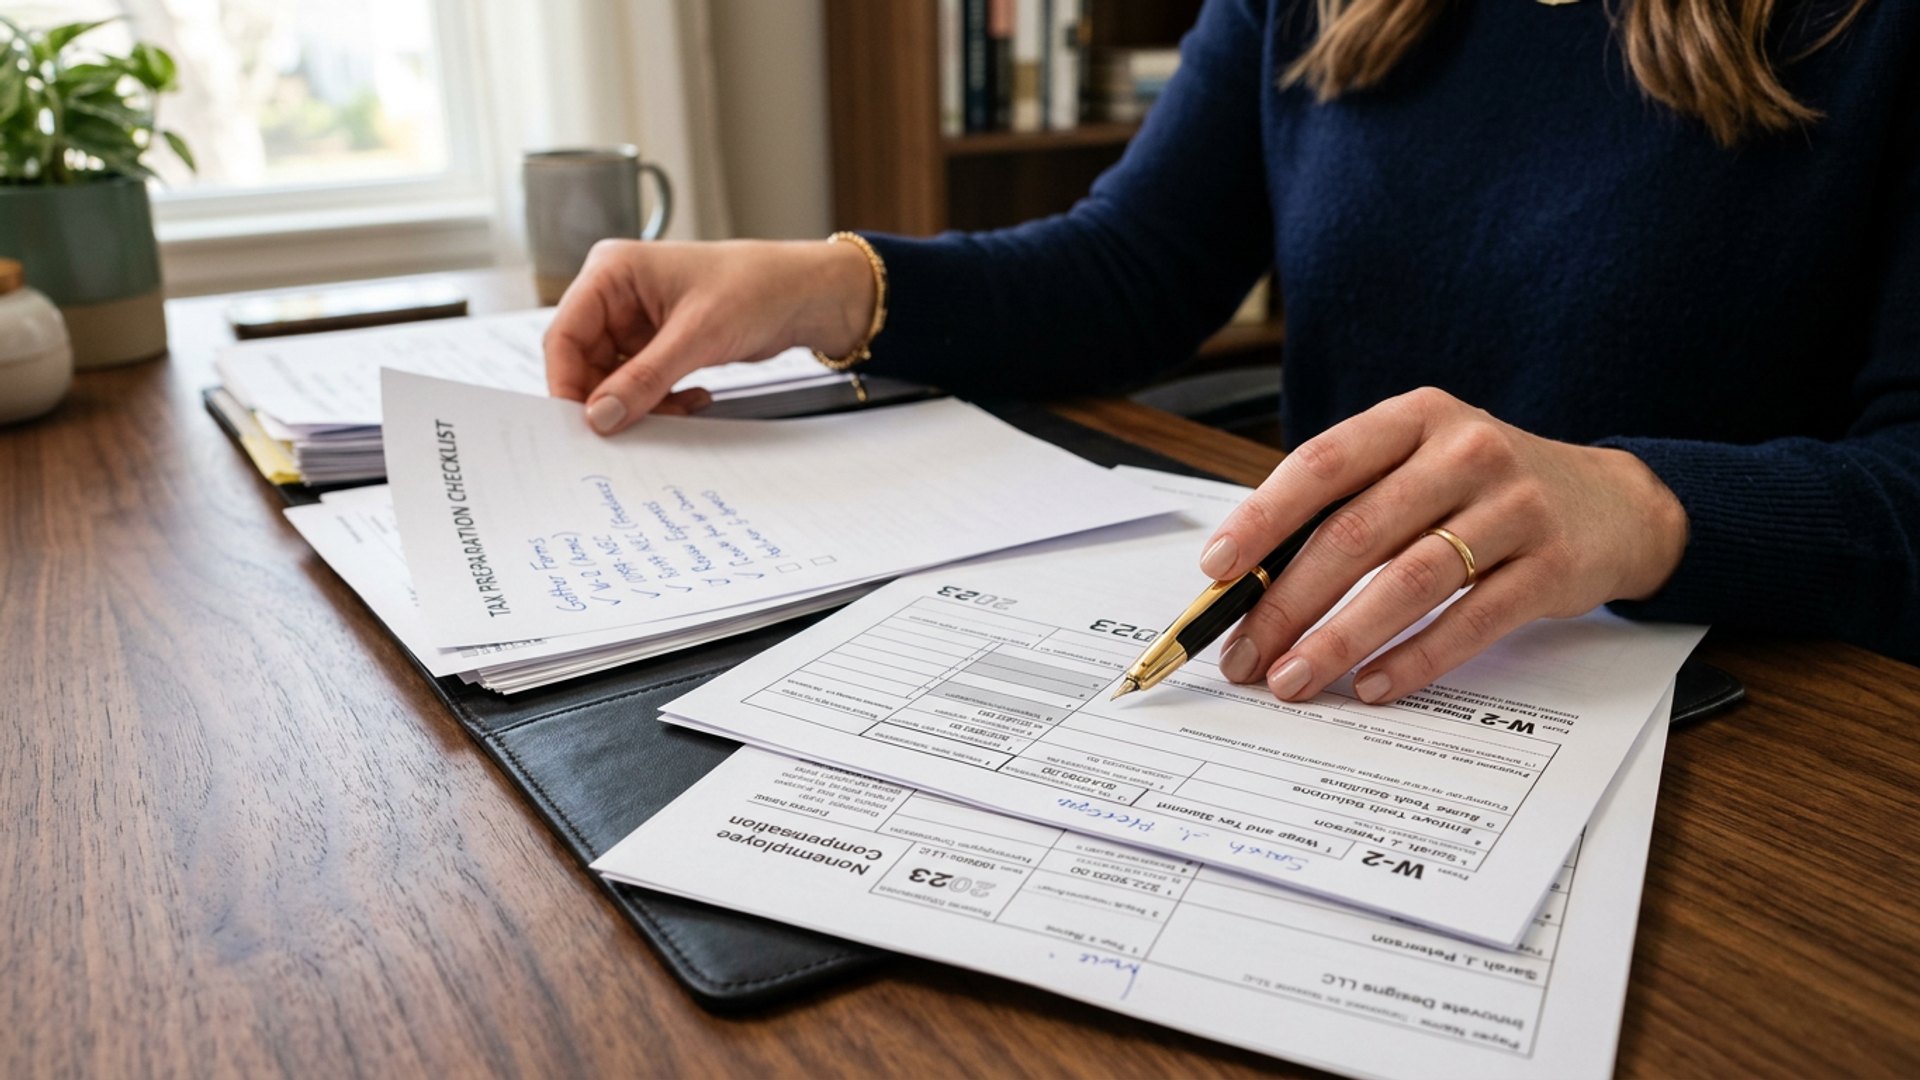
Start a folder, paper or digital, as soon as forms begin arriving in January. Most clients need:
- W-2 forms from every employer and 1099 forms for freelance, interest, dividend or retirement income
- Year-end statements from brokerage and investment accounts
- Records of rental income and expenses if you rent out a house or apartment
- Mortgage interest, property tax and charitable donation records
- Last year's tax return, which helps catch carryovers and changes
If you are self-employed or own a business, add your profit and loss records, mileage logs and receipts for business expenses. Clients with monthly bookkeeping already have most of this organized, because their records are completed every month instead of reconstructed in a rush.
A practical tip: do not wait until every form has arrived to start. Open the folder in early January, drop in what you already have, and add each new document as it comes. By the time the last 1099 shows up in February, your return is nearly ready to prepare.
Documents people forget most often
Some of the most commonly forgotten items are the ones that arrive quietly. Interest statements from a savings account you barely use, a 1099 for a short freelance project from last spring, a form from a retirement account you rolled over, or the property tax records for a co-op or second home. Health insurance marketplace forms and student loan interest statements also get overlooked. Before your appointment, scroll through your bank statements from the whole year and note every source of income, no matter how small. If money came in, there is usually a form for it, and the IRS receives a copy.
Common mistakes that cause IRS letters
Missing a 1099 is the most frequent reason clients receive an IRS notice. The IRS receives a copy of every form, so leaving one off almost always triggers a letter. Other common issues include forgetting estimated tax payments, reporting rental income without depreciation, and entering investment sales without the correct cost basis.
Filing too early can also backfire. If you file in late January and a corrected form arrives in March, you may need to amend the return, which adds time and cost. It is better to file once, correctly, with every document accounted for. If you are unsure whether a form applies to you, ask before filing rather than after the letter arrives.
Why rentals and investments need extra care
Owning a rental property or investment account changes your return in ways that are easy to get wrong. Depreciation, repairs versus improvements, and capital gains rules all affect how much you owe. A new roof on a rental is treated differently from a plumbing repair, and selling stock you have held for years is taxed differently from a quick trade. Our business tax filing work covers these situations every day, for both companies and individuals, so nothing is reported in the wrong place or at the wrong value.
If you own a business
Business owners have a longer checklist: profit and loss records, payroll reports, contractor payments, asset purchases and vehicle use. The cleanest business returns come from clean books, which is why so many of our business clients combine monthly bookkeeping with their annual filing. When the records are already organized, the return is a review instead of a reconstruction, and deductions are documented instead of estimated.
Plan for next year, not just this one
Once your return is filed, take a few minutes to look ahead. If you owed a large balance, tax planning can help you set estimated payments and avoid penalties next year. If you received a large refund, you may want to adjust your withholding so that money works for you during the year instead of sitting with the government. The best tax planning conversations happen right after filing, when the numbers are fresh.
How to organize everything before your appointment
A little organization before your appointment saves real time and money. Group your documents into simple piles: income forms in one, deduction records in another, business or rental records in a third. If you use our secure client portal, upload each document as it arrives instead of saving everything for one long session. Write down any questions as they occur to you, because the middle of an appointment is the easiest moment to forget them. If anything changed during the year, a move, a marriage, a new baby, a new business, a sold property, make a note of it. Life changes almost always have tax consequences, and mentioning them early lets us plan around them instead of discovering them at the end.
What happens after you file
The filing deadline in mid-April is the one everyone knows, but it is not the only one that matters. Estimated tax payments are due four times a year, in April, June, September and January, and missing them creates penalties even when your annual return is correct. Businesses have their own calendar: payroll filings each quarter, information forms like W-2 and 1099 due at the end of January, and entity returns due in March for many corporations and partnerships. If any of these apply to you, put them on the same calendar as the April deadline. A year of smooth compliance is really just a series of small deadlines met on time, and each one is much easier to meet when the records behind it are already organized.
Deadlines worth circling on the calendar
The filing deadline in mid-April is the one everyone knows, but it is not the only one that matters. Estimated tax payments are due four times a year, in April, June, September and January, and missing them creates penalties even when your annual return is correct. Businesses have their own calendar: payroll filings each quarter, information forms like W-2 and 1099 due at the end of January, and entity returns due in March for many corporations and partnerships. If any of these apply to you, put them on the same calendar as the April deadline. A year of smooth compliance is really just a series of small deadlines met on time, and each one is much easier to meet when the records behind it are already organized.
If you are self-employed
Self-employment income comes with its own checklist. Track every source of income, including platforms and clients that did not send a form, because the obligation to report does not depend on receiving one. Keep business expenses separate from personal ones, ideally with a dedicated account or card, and keep a mileage log if you use your car for work. Set aside a portion of every payment for taxes, because nothing is withheld for you. And consider whether quarterly estimated payments make sense, because waiting until April to pay a full year of tax almost always means penalties on top of the balance.
When it is time to stop doing it yourself
There is nothing wrong with preparing a simple return on your own. But certain signs mean professional help will likely save you more than it costs: you bought or sold a property, you started a business or side gig, you have income in more than one state, you received an IRS letter in the past, or you simply feel unsure whether you are claiming everything you should. A return that is slightly wrong in your favor becomes a letter and a penalty. A return that is slightly wrong against you is money you never get back. Either way, accuracy is the goal, and accuracy gets harder every year as life gets more interesting.
A final word on timing
The clients who have the calmest tax seasons share one habit: they start before they feel ready. You do not need every document in hand to make the appointment, and you do not need to understand every form to ask a question about it. Starting early means there is time to request a missing form, correct a wrong one and think about choices instead of rushing past them. It also means your return can be filed as soon as the season opens, which brings refunds sooner and leaves less room for identity thieves to file in your name first.
The bottom line: gather early, report everything and ask for help when your return becomes complex. During tax season we also work Saturdays and Sundays, so it is easier to fit your appointment into a busy schedule.
Written by